
Buyers Guide
Explore Our Trusted Partners
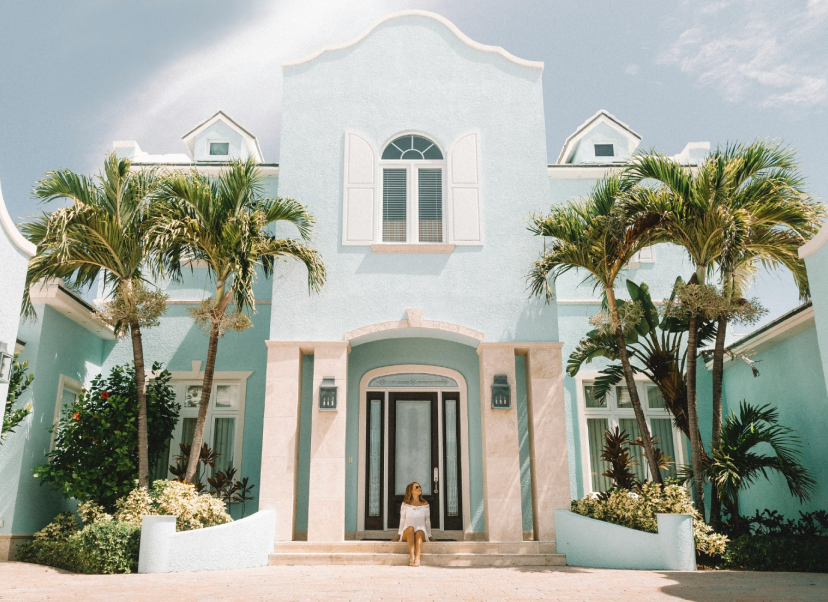
We represent you, it's our fiduciary duty to look after your interest
Buying a home can be a big challenge, whether you've done it before or not. It's easy to either choose the first place you can afford or keep renting. To make the process clearer and to help you get the best deal, let's look at what you need to think about before buying and what the buying process looks like.
First, decide what your long-term goals are and how owning a home fits with those plans. Some people want to turn their rent into mortgage payments that build equity. Others see owning a home as a way to be independent and be their own landlord. Additionally, some think of buying a home as a good investment.
Engage in your own Financial
Preparation
Before shopping for a home, find out how much a lender is willing to lend you. While you might think you can afford a $300,000 home, the lender's estimate could be lower, around $200,000, based on your debt, income, and job stability.
Get pre-approved for a loan before making an offer on a home, as many sellers won’t consider offers without mortgage preapproval. Realtors typically won't work with clients who haven’t determined their budget. Research lenders, compare interest rates and fees, and submit your mortgage application along with the required documents to verify your income and debt.
View and evaluate Potential Homes
You have different choices when buying a home: a single-family house, townhouse, condominium, co-operative, or multi-family building with two to four units. Each option has advantages and disadvantages based on your goals. You might also consider a fixer-upper to save money, but it can require a lot of time and effort to renovate. It’s important to create a list of what you want in a home, including location and features. Working Closely with a Realtor and/or real estate websites can help you find properties that meet your needs.
Steps in home buying
1. Find a Local Realtor
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Maecenas pellentesque libero nulla gravida imperdiet. Lorem ipsum dolor sit amet, consectetur adipiscing elit. Maecenas pellentesque libero nulla gravida imperdiet aliquam. Lorem ipsum dolor sitamet, consectetur adipiscing elit. Maecenas pellentesque libero nulla gravida imperdiet. Maecenas pellentesque libero nulla gravida imperdiet aliquam. Lorem ipsum dolor sit amet, consectetur. Maecenas pellentesque libero nulla gravida imperdiet aliquam. Sit amet consectetur.
consectetur adipiscing elit. Maecenas pellentesque libero nulla gravida imperdiet. Maecenas pellentesque libero nulla gravida imperdiet aliquam. Lorem ipsum dolor sit amet, consectetur.
3. Pre-Qualification
It is important to have your personal finances organized before applying for a home loan. To qualify, you typically need good credit, timely bill payments, and a debt-to-income ratio of no more than 43%. Lenders usually prefer that monthly housing costs make up about 28% of your gross income, but this can differ based on the local market.
After applying, the lender will check your financial details and may pre-approve you for a loan amount. However, changes to your credit score can jeopardize this approval. Don't feel tied to your current bank; compare lenders for better fees and interest rates. It's also wise to have a backup lender, as loan funding can be unexpectedly delayed or even canceled.
5. Due Diligence
Even if the home looks perfect, it’s important to have a professional inspect it for quality, safety, and condition. If serious problems are found that the seller didn’t mention, you can usually cancel your offer and get your deposit back. You might also negotiate for the seller to make repairs or lower the price.
If you reach an agreement with the seller or find no major issues, be prepared to close. Closing involves signing many documents quickly and ensuring nothing goes wrong at the last moment. You may need to handle costs like a home appraisal, a title search, and private mortgage insurance.
2. Home Search
Make sure to explore all options for finding homes, like using a real estate agent, searching online, and driving around to spot for-sale signs. Reach out to friends, family, and business contacts for leads or references.
When you start house hunting, don’t go to open houses without an agent or at least planning to mention someone you’re working with. It’s best not to engage with the seller's agent without your own representation.
If you're on a budget, consider homes that need some work. Even if you can't fix certain things right away, focus on the necessary aspects like location and size. First-time buyers should aim for homes they can improve to increase their equity.
4. Offer Process
Your real estate agent will help you decide how much to offer for the house and any conditions, like having the buyer cover closing costs. The agent presents your offer to the seller's agent, who will either accept it or make a counteroffer. You can then negotiate until you agree or choose to stop.
Before making an offer, review your budget by including estimated closing costs, commuting costs, and any urgent repairs or appliances needed. Consider potential higher costs like utilities and property taxes. If an agreement is made, you will make a good-faith deposit, and the process moves into escrow, usually around 30 days, while you inspect the house.
 Copyright © MFRMLS.com All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information on this site was last updated Last updated on September 23, 2026 6:14 AM UTC The listing information on this page last changed on Last updated on September 23, 2026 6:14 AM UTCd. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of MFR MLS.
All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Updated on September 23, 2026 6:14 AM UTC
 Copyright Southeast Florida Multiple Listing Service © 2026. Accuracy of listing information is not guaranteed. Listing information is provided for personal consumer, non-commercial use, solely to identify potential properties for potential purchase. All other use is strictly prohibited, is a violation of the terms of use, and may violate federal and state law.
Data Last Updated: September 23, 2026 6:21 AM UTC
 Copyright © 2026 by the Multiple Listing Service of the Pensacola Association of
REALTORS ® This information is believed to be accurate but is not guaranteed. Subject to verification by all parties. This data is copyrighted and may not be transmitted, re-transmitted, copied, framed, re-purposed, or altered in any way for any other site, individual and/or purpose without the express written permission of the Multiple Listing Service of the Pensacola Association of REALTORS ®. Florida
 IDX information is provided exclusively for consumer's personal, non-commercial use. Data may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Data is deemed reliable but not guaranteed.
The Tallahassee Board of REALTORS® Inc Data on this site was last updated: September 23, 2026 6:11 AM UTC
 All information regarding a property for sale, rental or financing, school information and public tax records is from sources deemed reliable; PROVIDED, HOWEVER, that representations and warranties are not made about the accuracy thereof, and such information is subject to errors, omissions, updates, modifications, changes of price, rent rates, commissions, prior sales, leases or financing, changes in school boundaries, or withdrawal without notice. All information displayed on this Website should
 © 2026 Florida Gulf Coast MLS (FGCMLS) Information deemed reliable, but not guaranteed. The IDX data relating to real estate for sale on this web site comes in part from the Florida Gulf Coast Multiple Listing Service. The information being provided is for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is deemed reliable but not guaranteed.
 This data is up-to-date as of September 23, 2026 6:13 AM UTC Some properties that appear for sale on this website may subsequently have sold and may no longer be available. For the most current information, contact Allison James Estates and Homes - Florida.
The information provided is for consumers' personal, non-commercial use and may not be used for any other purpose. The data relating to real estate for sale on this website comes in part from the Broker Reciprocity Program (BR Program) of
 The data relating to real estate for sale/lease on this web site come in part from a cooperative data exchange program of the multiple listing service (MLS) in which this real estate firm (Broker) participates. The data is provided exclusively for the user's personal non-commercial use, and may not be used for any purpose other than to identify properties that the user may be interested in purchasing or leasing. The properties displayed may not be all of the properties in the MLS's database, or all
 Information is deemed to be reliable, but is not guaranteed. © 2026 MLS. Last Updated September 23, 2026 5:51 AM UTC The information on this sheet has been made available by the MLS and may not be the listing of the provider. Listing data provided by the Daytona Beach Area Association of REALTORS® Internet Data Exchange (IDX) program. Data is believed to be accurate but not warranted.
 These listings are provided by the IDX Program of Brevard County, Florida. Real Estate listings held by brokerage firms other than Allison James Estates and Homes - Florida are marked with the IDX Logo and detailed information about them includes the name of the listing brokers. IDX information is provided exclusively for consumers' personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
